GST ITC Reversal Rules 2026: 180-Day Payment Rule, GSTR-2B Matching, and Re-Availment
Complete guide to GST ITC reversal under Rule 37 (180-day vendor payment rule) and Rule 37A (vendor GSTR-3B default). Learn interest rules & re-availment.
BillBabu Team
BillBabu Compliance Team
In this article (15 sections)
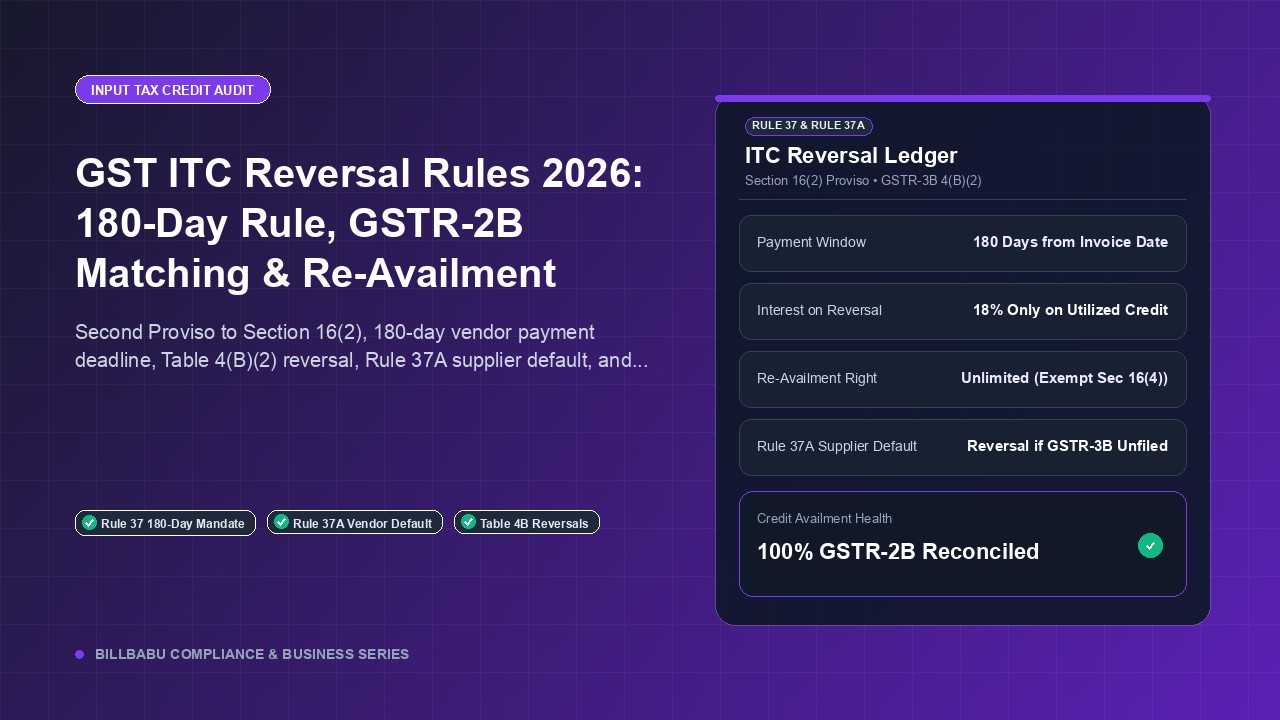
Under the Goods and Services Tax (GST) framework, Input Tax Credit (ITC) is the lifeblood of business liquidity. However, claiming ITC on an inward invoice is not an unconditional right. Under the second proviso to Section 16(2) of the CGST Act read with Rule 37, every recipient must pay the supplier the full invoice value along with applicable tax within 180 calendar days from the date of the invoice. If the buyer defaults on payment past 180 days, the entire ITC claimed must be reversed with 18% interest! In addition, Rule 37A penalizes buyers when their suppliers fail to file GSTR-3B returns. In 2026, with GST scrutiny algorithms cross-matching bank books and vendor ledgers, mastering ITC reversal, interest exposure, and subsequent re-availment protocols is essential for every Indian enterprise.
The Statutory Foundation: Section 16(2) Second Proviso
To avail and retain Input Tax Credit, a registered buyer must satisfy four primary conditions under Section 16(2):
- Possession of a valid Tax Invoice or Debit Note.
- Details of the invoice reflected in GSTR-2B.
- Actual receipt of the goods or services.
- The supplier having paid the tax to the government and filed GSTR-3B.
To these four conditions, the Second Proviso to Section 16(2) adds a strict operational mandate:
The 180-Day Rule: Where a recipient fails to pay to the supplier of goods or services, the amount towards the value of supply along with tax payable thereon within a period of one hundred and eighty days (180 days) from the date of issue of invoice, an amount equal to the input tax credit availed by the recipient shall be paid by him along with interest payable under Section 50.
Mechanics of Rule 37: Reversal Reporting & Interest Calculations
When the 180-day statutory clock runs out, how must a business execute the reversal?
1. Counting the 180 Days
The time limit is counted strictly as 180 calendar days from the date of issuance of the invoice (not from the date of delivery, and not from the end of the month). For an invoice dated 1st October 2025, the 180-day window expires on 30th March 2026.
2. Reporting in GSTR-3B
The reversal must be declared in Table 4(B)(2) ("Others") of Form GSTR-3B for the tax period immediately following the expiry of 180 days. This reverses the tax credit from your electronic credit ledger or adds it to your cash tax liability.
3. Interest Liability Under Section 50
Under Section 50(1) read with Rule 88B, interest at 18% per annum is payable. However, following landmark statutory amendments:
- Interest is payable ONLY if the reversed ITC was actually utilized to set off output tax liability!
- If the ITC remained as an unutilized balance in your Electronic Credit Ledger from the date of availing until the date of reversal, zero interest is payable under Section 50(3).
Create GST invoices & track payments in 30 seconds
Join thousands of Indian businesses using BillBabu. 14-day free trial on Android.
The Third Proviso to Section 16(2): Unlimited Re-Availment
What happens when the buyer finally clears the overdue bill with the supplier?
Under the Third Proviso to Section 16(2), whenever the recipient subsequently pays the supplier the outstanding invoice value plus tax, the recipient is legally entitled to re-avail the reversed Input Tax Credit in full!
The Critical Section 16(4) Exemption: Standard statutory time limits to claim ITC—which cut off claims on 30th November following the end of the financial year—do NOT apply to re-availment under Rule 37! You can re-avail the credit even two or three years later upon making payment.
How to Report Re-Availment in GSTR-3B:
- Add the reclaimed ITC in Table 4(A)(5) ("All other ITC") to credit your ledger.
- Simultaneously report the exact reclaimed sum in Table 4(D)(1) ("ITC reclaimed which was reversed under Table 4(B)(2) in earlier tax period") for automated reconciliation tracking.
Rule 37A: Reversal Due to Vendor GSTR-3B Default
While Rule 37 penalizes buyers for non-payment, Rule 37A addresses defaulting vendors:
- The Trigger: Your supplier issues an invoice, reports it in their GSTR-1 (so it appears in your GSTR-2B), and you pay the vendor in full. However, the supplier fails to file their GSTR-3B return!
- Statutory Deadline: If the supplier does not file GSTR-3B by 30th September following the end of the financial year, the buyer must reverse the corresponding ITC on or before 30th November.
- Zero Interest Window: If the buyer reverses the credit by 30th November, no interest is payable! If reversed after 30th November, 18% interest applies from 1st December.
- Re-Availment: When the defaulting vendor eventually files GSTR-3B, the buyer can re-avail the reversed ITC in Table 4(A)(5).
Side-by-Side Comparison: Rule 37 vs. Rule 37A
| Compliance Dimension | Rule 37 (180-Day Payment Rule) | Rule 37A (Vendor Return Default) |
|---|---|---|
| Root Cause | Buyer failed to pay vendor within 180 days | Vendor failed to file GSTR-3B return |
| Reversal Trigger Date | 180 days from invoice issuance date | By 30th November of subsequent FY |
| Interest Rate | 18% per annum from date of utilization | 0% if reversed by Nov 30; 18% thereafter |
| Re-Availment Trigger | When buyer finally pays the vendor | When vendor finally files GSTR-3B |
| Time Limit to Re-Avail | NO TIME LIMIT (Exempt from 16(4)) | NO TIME LIMIT (Exempt from 16(4)) |
Full Worked Financial Example (Reversal & Re-Availment)
Delta Manufacturing purchases industrial tools from an intrastate vendor on 10th August 2025 for ₹5,00,000 plus 18% GST (₹90,000) = ₹5,90,000. Delta claims ₹90,000 ITC in their August 2025 GSTR-3B and utilizes it against September sales.
- 180-Day Expiry: 180 days from 10th August 2025 expires on 6th February 2026. Delta has paid ₹0 to the vendor due to working capital constraints.
- February 2026 GSTR-3B Reversal: In GSTR-3B filed on 20th March 2026, Delta reverses ₹90,000 in Table 4(B)(2). They pay 18% interest on ₹90,000 from the date of utilization to 20th March 2026 (~₹8,000).
- Settlement with Vendor: On 15th May 2026, Delta remits the full ₹5,90,000 to the vendor.
- May 2026 GSTR-3B Re-Availment: In GSTR-3B for May 2026, Delta re-avails the full ₹90,000 in Table 4(A)(5) and reports it in Table 4(D)(1). Liquidity is fully restored.
Automate 180-Day Rule 37 & 37A Tracking in BillBabu
Never pay avoidable 18% interest on forgotten vendor bills. BillBabu monitors invoice aging across all purchase bills, sends automated 150-day and 170-day alerts before the 180-day deadline, tracks GSTR-2B compliance, and auto-populates Table 4(B)(2) reversal sheets.
Start Free Trial on BillBabuFrequently Asked Questions (FAQs)
1. What happens if a buyer makes partial payment within 180 days?
If partial payment is made (e.g., 60% of the invoice value is paid within 180 days), the buyer is required to reverse only the proportionate ITC corresponding to the unpaid 40% balance.
2. Does Rule 37 apply to Reverse Charge Mechanism (RCM) supplies?
No. Under the proviso to Rule 37(1), supplies subject to Reverse Charge (where the recipient pays GST directly to the government, such as GTA freight or legal fees) are exempt from the 180-day payment rule.
3. Are retention money and security deposits subject to 180-day reversal?
CBIC has clarified through circulars that where contractual agreements permit retention of a percentage of the contract value (e.g., 10% performance guarantee retention payable after warranty expiry), such retention does not trigger Rule 37 reversal, provided the undisputed invoice value is paid within terms.
Tags
Related Articles
E-Way Bill Rules 2026: Distance Validity, State-Wise Thresholds, and Consolidated E-Way Bills
6 min read
Credit Note and Debit Note in GST: Time Limits, GSTR-1 Reporting, and Accounting Entries
6 min read
MSME 45-Day Payment Rule under Section 43B(h): Rules, Penalties, and Year-End Compliance for 2026
7 min read
GST invoicing made easy for Indian small businesses
Create GST-compliant invoices & estimates, track payments, manage parties and inventory — all from your phone. 14-day free trial, no credit card needed.